The Unexpected Shock: When Your Three-Digit Number Drops
You finally decide to buy that car, hand over your ID for a quick financing check, and bam—your phone buzzes. Your banking app alerts you that your credit score just took a dive.
Why does doing something completely normal, like applying for a loan, feel like an instant financial punishment? If you are scratching your head over those suddenly missing points, you are not alone. When I first saw my own score drop just because I wanted to check my options, I panicked too. Let us break down exactly what just happened behind the scenes, why lenders do this, and how you can bounce back fast without losing your peace of mind.
Quick Summary: What You Need to Know
- A drop is normal: Your score dips slightly when you apply for credit because lenders are double-checking your current debt limits.
- Soft vs. Hard pulls: Checking your own score never hurts you (Soft). Applying for new money does (Hard).
- The 14-day rule: You can apply to multiple auto or home lenders within 14 days, and it only counts as one single hit.
- Fast recovery: The small point drop usually bounces back completely within 3 to 6 months of on-time payments.
Why Does It Feel Like a Punishment
Did I do something wrong by applying for a loan?
Absolutely not. Applying for new credit is a completely normal part of adult life. The system is just designed to flag sudden requests for money as a potential risk.
Will this small drop ruin my financial future?
No, it will not. The initial sting feels awful, but it is actually a temporary situation. The anxiety you feel is real, but the long-term damage is usually minimal.
Breaking Down the Credit Check Process
When you ask a bank or a lender for money, they need a way to measure how much of a risk you are. Think of your credit report as a financial resume. Just like an employer calls your references before offering you a job, a lender pulls your report to see how you handled money in the past.
This process of pulling your report is known as an inquiry. However, not all inquiries are treated the same way by the scoring algorithms. The system splits these background checks into two very different categories.
Understanding this split is the most important step in taking back control of your financial confidence. Once you know exactly what lenders are looking for, you can apply for new loans without the constant fear of unexpected penalties.
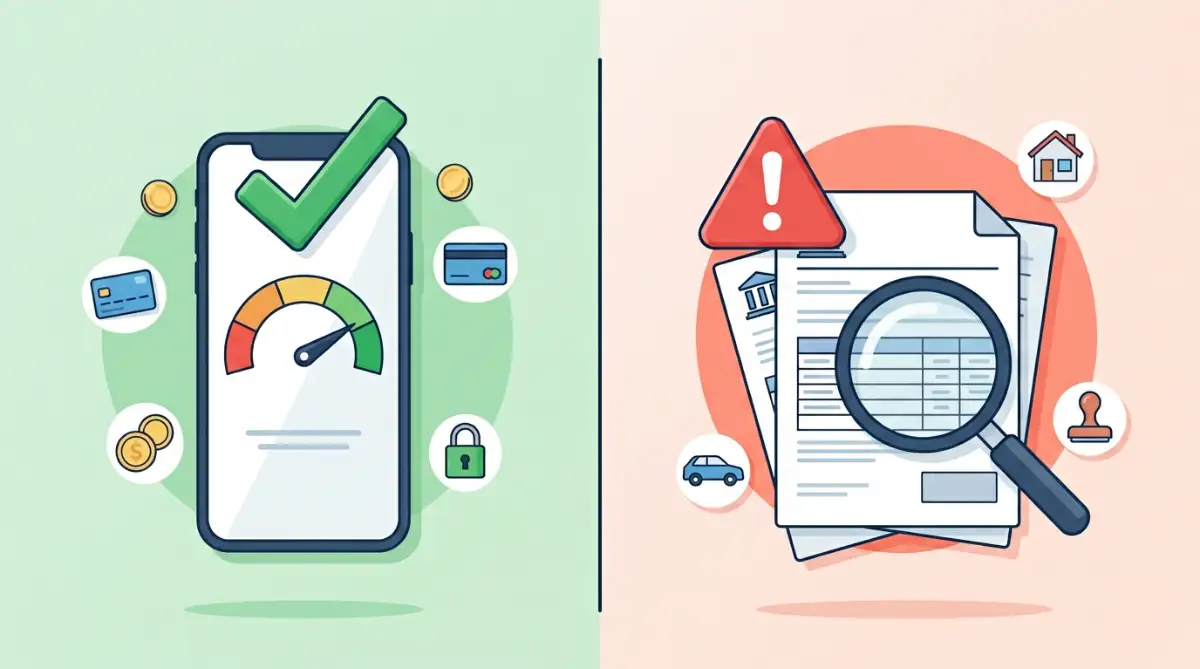
The Real Difference Between Hard and Soft Checks
To make this incredibly simple to understand, let us look at a direct comparison of the two types of checks.
As you can see, the intent behind the check is what really matters to the algorithms. If you are just browsing or checking up on your own health, the system does not care. But if you are actively asking to borrow money, the system pays close attention.
Why Do Scoring Models Penalize New Applications?
You might still be wondering why actively asking for a loan results in a penalty. The logic behind the algorithm is actually based on heavy statistical data and human behavior patterns.
Data shows that people who apply for several different lines of credit in a very short amount of time are often facing financial trouble. Imagine someone applying for five different credit cards in a single week. To a computer algorithm, this looks like someone who desperately needs cash to stay afloat.
Therefore, every time a lender pulls your full report to approve a loan, the algorithm shaves off a few points. It is basically the system's way of hitting the pause button to see how you will handle this new potential debt.
Pro Tip from My Own Experience:
I used to think spreading out my credit card applications over six months was the smart way to handle things. I quickly realized this kept extending the penalty period, keeping my score artificially low for a much longer time. It is actually much better to group your planned applications strategically so your score has plenty of uninterrupted time to recover.
The "Rate Shopping" Buffer Zone
Now, let us talk about a fantastic built-in protection that most everyday consumers do not even know exists. It is called the rate shopping window, and it is a complete game-changer when you need a big loan.
When you buy a house or a car, it is basic common sense to talk to multiple lenders to find the lowest interest rate. The people who designed the credit scoring models actually understand this. They know that applying for five auto loans in one week does not mean you want to buy five cars. It means you want to buy one car and find the best deal.
Because of this, modern scoring models group similar hard inquiries together if they happen within a specific timeframe. Depending on the exact scoring model the lender uses, this safe window is usually between 14 to 45 days.
To help you plan your applications, here is a quick breakdown of how different scoring models treat your rate-shopping window:
Quick Tip: Since you rarely know which exact version a lender will pull, play it safe and try to wrap up all your rate shopping within a strict 14-day timeline.
During this window, you can apply to five, ten, or even fifteen different auto or mortgage lenders. While every single check will show up on your written report, the algorithm will only deduct points for one single inquiry. This completely changes the way you should approach shopping for big loans.
How to shop smart without fear:
- Gather all your financial documents before you start applying anywhere.
- Submit all your mortgage or auto loan applications within a focused two-week period.
- Never mix different types of credit during this window. If you are shopping for a car loan, do not apply for a new credit card on the same day.
Watch This Quick Explanation Before You Apply:
If you are planning to apply for a loan soon, you absolutely need to understand how the rate shopping window protects you. This short, eye-opening video breaks down exactly how to check rates with multiple banks without trashing your hard-earned number.
How Much Will Your Number Actually Drop?
One of the biggest sources of anxiety is the fear of the unknown. People often imagine that a single loan application will send their score crashing down by fifty or a hundred points.
In reality, the damage from a single hard inquiry is usually very small. For most people with a healthy financial history, one inquiry will drop their score by less than five points. Often, it might only be two or three points.
If you have a very short credit history or only a few active accounts, the impact might be slightly higher. However, it is almost never the massive financial disaster that people build it up to be in their heads.
The algorithm looks at your entire financial picture. If you have a solid track record of paying your bills on time, a small five-point drop is essentially meaningless. It will not stop yo