The Hidden Numbers That Control Your Financial Dreams
Forget the boring financial advice for a second. Why does a bank happily approve your neighbor for a massive $300,000 mortgage, but instantly reject you for a simple $10,000 car loan—even when you both earn the exact same salary? It all comes down to a silent background check called your Debt-to-Income (DTI) ratio. I will show you exactly how lenders use this simple math formula to judge your money, and more importantly, how you can hack your own numbers so they always say yes.
Your 30-Second Financial Blueprint
- Your DTI ratio is the exact mathematical formula banks use to see if you can actually afford a new loan.
- You can calculate it right now by simply dividing your total minimum monthly debt payments by your gross monthly income.
- Always aim for a ratio under 36% to lock in the lowest interest rates and get faster approvals.
- Wiping out tiny "micro-debts" (like a $20 store card minimum payment) is the fastest way to instantly boost your numbers before walking into a bank.
Decoding the Formula: Why Lenders Care So Much
Before we jump into the exact math, we need to understand what this ratio actually represents in the real world. Think of your gross monthly income as a sturdy bridge that you walk across every single day. Your monthly debt payments are the heavy rocks you carry in a backpack while crossing that bridge.
They are essentially trying to measure your financial breathing room. If you lose your job, face a medical emergency, or deal with sudden home repairs, will you still be able to pay them back?
Your DTI is the most honest reflection of your financial safety net. While your credit score tells a lender how consistently you pay your bills, your DTI tells them if you actually have the cash flow to afford a new one. Understanding this difference changes completely how you look at your own money.
Step 1: Tracking Down Your True Monthly Income
The first part of our calculation is figuring out exactly how much money you bring in before the government takes their slice. We are looking for your gross monthly income, which simply means your total earnings before taxes and deductions are removed.
For most people who work a standard job with a regular salary, finding this number is quite easy. You just look at your pay stub and find the "gross pay" line, or divide your total annual salary by twelve. But life is rarely that simple, and many of us have multiple streams of income these days.
If you work hourly and your schedule changes, you need to calculate an average based on your past few months of paychecks. You can also include side hustles, freelance work, and gig economy earnings. However, lenders usually require you to show a steady history of this extra income, often spanning two full tax seasons.
You can also count things like alimony, child support, and consistent bonus payments. The key here is consistency and proof. If you cannot prove it with a bank statement or a tax return, a bank will not count it toward your calculation.
Pro Tip: When I first tried to calculate my own numbers, I completely forgot to include the regular overtime pay I received every single month. Always review your last few pay stubs carefully, because missing a few hundred dollars of verifiable income can severely hurt your final ratio!
Step 2: Gathering Your Monthly Debt Obligations
Now we need to look at the other side of the scale, which is often the part that makes people the most nervous. You need to gather every single recurring debt payment that shows up on your credit report. This is where many people make a massive mistake by including the wrong types of expenses.
We are strictly looking for actual debt obligations, not your general living expenses. You must include your rent or current mortgage, car loans, personal loans, and minimum credit card payments. Student loans and any legally required child support or alimony payments also belong on this list.
What you should leave out is just as important as what you include. Do not add your monthly grocery bills, health insurance premiums, Netflix subscriptions, or regular utility bills. Even though these take money out of your pocket, lenders do not consider them fixed debts.
Let us say you pay off your credit card balance in full every single month to earn travel points. For this calculation, you only need to look at the minimum required payment listed on your statement, not the full balance you plan to pay off.
The Core Calculation: Bringing Your Numbers Together
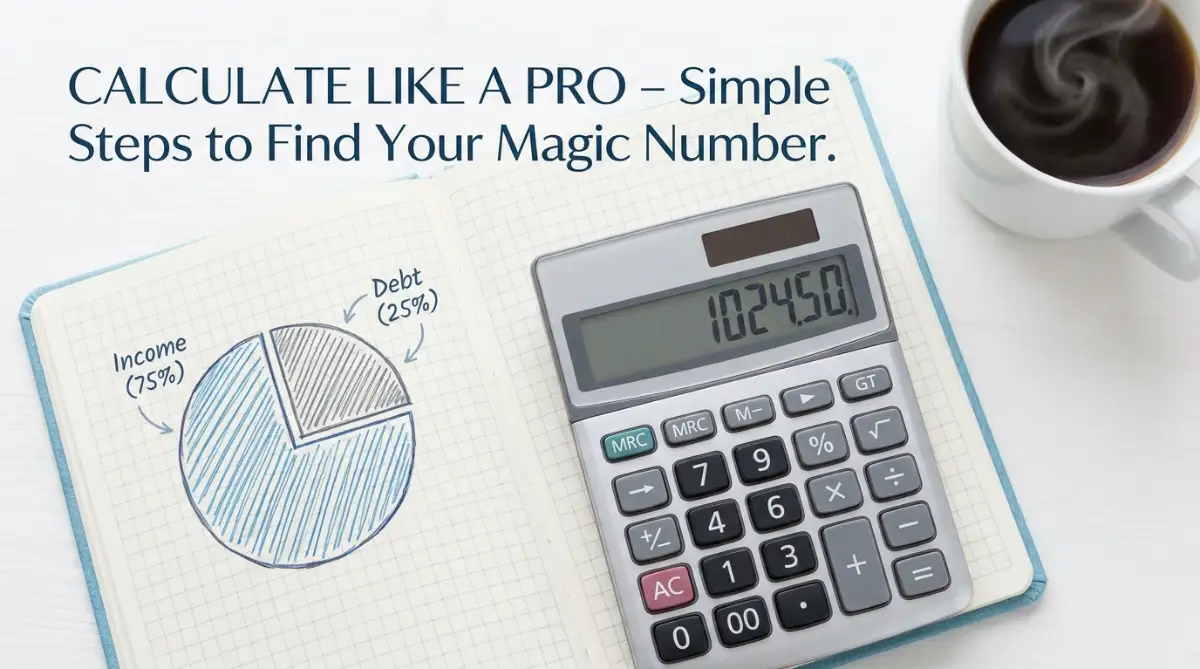
Once you have your total gross income and your total monthly debt, the actual math is incredibly simple. You do not need a fancy degree in finance to figure this out. You simply divide your total monthly debt by your total gross monthly income.
After you divide those two numbers, you multiply the result by 100 to turn it into a clear percentage. Let us walk through a very common, real-world example to make this perfectly clear.
Before we look at Sarah's math, here is a quick cheat sheet showing exactly how lenders view your final percentage:
Imagine a woman named Sarah who brings home a gross income of $6,000 every single month from her teaching job. She pays $1,200 for rent, $300 for her car loan, $200 for student loans, and has a $100 minimum payment across her credit cards.
Sarah’s total monthly debt equals $1,800. We take her $1,800 in debt and divide it by her $6,000 income, which gives us 0.30. Multiply that by 100, and Sarah has a healthy ratio of exactly 30%.
Struggling to visualize the math behind your debt? Watch this quick breakdown that makes calculating your numbers easier than ever.
The Magic Numbers: Where Do You Actually Stand?
Now that you have your percentage written down, you are probably wondering if your number is good or bad. Lenders generally group these percentages into a few different categories to assess risk.
If your number is 36% or lower, you are sitting in a very strong financial position. Banks love to see numbers in this range because it proves you have plenty of leftover cash for daily life and unexpected emergencies. You will likely get the best interest rates available with this score.
When your number creeps up between 37% and 43%, you enter a caution zone. Many lenders will still approve you for a mortgage or personal loan, but they will look much closer at your application. You might need a higher credit score or a larger down payment to convince them you are safe.
Anything above 43% is generally considered a high risk by traditional banking standards. This was exactly where I was sitting during my failed bank appointment. At this level, getting approved becomes incredibly difficult, and if you do, you will face very high interest rates.
Different Loans Have Different Rules
It is important to remember that not all loans share the exact same strict limits. A conventional mortgage usually strongly prefers a maximum ratio of 36% to 43%. They are the most traditional and often have the tightest rules regarding your monthly obligations.
Government-backed loans often provide a lot more flexibility for average buyers. For example, an FHA loan might allow a ratio as high as 50% in certain situations, provided you have other compensating factors. VA loans for veterans also offer more generous guidelines to help families secure homes.
If you are applying for an auto loan or a personal unsecured loan, the rules can vary wildly from bank to bank. Some aggressive lenders might accept a 50% ratio, but the hidden cost will always be a brutal interest rate that keeps you trapped.
Practical Strategies to Improve Your Ratio
If you just calculated your number and feel a wave of panic, please take a deep breath. This percentage is not a permanent tattoo; it is just a temporary snapshot of your current situation. You have the total power to change this number before you ever sit down with a loan officer.
You only have two paths to fix a bad ratio: decrease your debt or increase your income. Doing both at the same time is the ultimate financial superpower.
The Fast Path: Attacking Your Debt
The quickest way to lower your percentage is to aggressively pay down your smallest debts first. If you have a credit card with a $500 balance that requires a $50 monthly payment, wipe it out immediately.
By eliminating that entire debt, you instantly remove $50 from your monthly debt calculation. It might not sound like a massive amount, but dropping two or three small minimum payments can drop your overall ratio by several percentage points.
Another powerful strategy is debt consolidation. If you have five credit cards with high interest rates and high minimum payments, you can combine them. Taking out a single, lower-interest personal loan to pay them off can drastically reduce your total required monthly payment.
The Sustainable Path: Boosting Your Income
Increasing your income takes a bit more effort, but it completely changes your financial picture. Remember, banks look at gross income, so even a modest raise at work makes a huge difference.
Consider taking on extra shifts, asking for a long-overdue promotion, or finding a weekend side job. If you add just $500 to your monthly gross income, the denominator in your calculation grows. A larger denominator instantly shrinks your percentage, making you look much safer on paper.
Just remember the golden rule of extra income: it must be verifiable. Keep excellent records, deposit everything into a real bank account, and claim it on your taxes. A cash tip job is great for your pocket, but it does absolutely nothing for your loan application if you hide the money.
Quick Q&A: Will the bank count my side hustle?
Question: I make an extra $800 a month driving for Uber and selling things online. Can I add this to my income?
Answer: Only if you can back it up! Most lenders want to see at least two full years of consistent gig economy tax returns before they trust that extra money. If you just started your side hustle last month, the underwriter will not count a single penny of it yet.
Common Myths That Trick Honest Borrowers
There is so much terrible advice floating around the internet regarding loan approvals. Let us clear up a few massive misunderstandings that trick smart people every single day.
Taking Control of Your Financial Future
Understanding these hidden calculations gives you back the power. You are no longer stepping into a bank hoping for good luck or begging for a favor. You can walk into that office knowing your exact numbers and knowing exactly what you qualify for.
Start by sitting down this weekend with a cup of coffee and your latest statements. Do the math yourself, without any pressure or judgment. If the number is too high, make a realistic plan today to chop down those minimum payments one by one.
Financial freedom is not always about making millions of dollars. Sometimes, it is simply about knowing the rules of the game and playing them better than anyone else. Protect your income, manage your obligations, and the approvals will naturally follow.
Advanced Strategies to Master Your Monthly Numbers
Knowing your math is just the starting point of your financial journey. If you want to walk into a bank with total confidence, you need to actively manage and manipulate these numbers in your favor. The most successful borrowers treat their monthly obligations like a game of strategy.
One of the smartest moves you can make is restructuring your current liabilities before you ever apply for new funds. If you have a car note with a massive monthly requirement, look into refinancing that specific vehicle to stretch the term. While this might cost a little more in long-term interest, it instantly drops your required monthly payment.
A lower monthly payment means a significantly better ratio on paper. This small trick alone can easily bump you from a rejection to an instant approval. You should always aim to secure the best personal loan rates when restructuring your current obligations.
Another powerful expert secret involves timing your application perfectly with your income cycle. If you work a job that pays annual bonuses or heavy seasonal commissions, do not apply during your slow months. Lenders want to see a consistent average, so wait until you have a solid string of high-earning pay stubs to show them.
For freelancers and business owners, the rules are slightly different but equally manageable. Banks usually look at your net income after heavy business write-offs, which can accidentally make you look poor on paper. You might need to claim fewer business expenses on your taxes for a season to show a higher personal income to the bank.
The Art of Wiping Out Micro-Debts
Most people focus completely on their massive, intimidating debts like huge student loans or expensive cars. However, the secret to a fast approval often hides in your smallest, most annoying monthly bills. We call these micro-debts, and they are secretly ruining your percentages.
Let us say you have a credit card from a local electronics store with a balance of just $300. The minimum monthly payment might be $45, which feels incredibly easy to manage. But to a bank's computer system, that $45 is eating into your usable monthly cash flow.
If you take a portion of your savings and wipe out that $300 balance completely, that $45 obligation vanishes. Eliminating three or four of these tiny accounts can suddenly free up hundreds of dollars in your calculation. It is a highly effective way to clean up your profile without needing a massive pile of cash.
Before you make any big moves, I highly recommend reviewing the guidelines on managing personal debt provided by the Consumer Financial Protection Bureau. Their official resources offer fantastic insights into how government regulators view consumer borrowing.
Navigating the Co-Borrower Hack
Sometimes, no matter how hard you try to clear your accounts, your numbers simply will not match the bank's requirements. This is exactly when you should consider bringing a trusted co-borrower into the equation. A co-borrower allows you to combine your incomes, which drastically changes the mathematical outcome.
If you apply with a spouse or a family member, the lender will add both of your gross monthly incomes together. They will also add both of your monthly liabilities together to create a single, blended percentage. If your partner has a high income and very little debt, their strong profile will easily balance out your weaker one.
However, you must have complete trust and transparency with anyone you invite onto your application. You are both equally responsible for the entire borrowed amount, and any missed payments will ruin both of your credit profiles. Always make sure you completely understand how secured loans and collateral work before tying someone else to your property.
The Hidden Traps That Destroy Loan Applications
Even the smartest people make terrible financial mistakes simply because they do not understand how an underwriter thinks. An underwriter is the person at the bank who double-checks your life and ultimately decides if you get the money. They are trained to look for specific warning signs that tell them you are a high-risk customer.
One of the most heartbreaking situations I ever witnessed involved a close friend who was three days away from buying his dream home. He was fully approved, his ratios were perfect, and he was already packing his boxes. To celebrate, he went out and financed a brand-new set of expensive living room furniture.
The furniture store ran his credit, created a new monthly payment of $150, and instantly reported it to the bureaus. The mortgage lender did a final check the day before closing, saw the new debt, and recalculated his numbers. That simple $150 payment pushed his ratio over the maximum limit, and he lost the entire house on the spot.
You must act like a financial ghost while you are waiting for an approval. Do not apply for store cards, do not finance a new mattress, and absolutely do not buy a car. If you fall into this trap, it becomes one of the most common reasons banks say no to your request.
The Danger of Helping a Friend
Another massive trap that catches kind-hearted people is the act of co-signing a loan for a family member or friend. You might think you are just doing a quick favor to help your nephew get his first reliable car. You sign the paper, he drives away, and you completely forget about it because he pays the bill every month.
Unfortunately, the banking system does not care who drives the car or who writes the check. Because your name is on that legal contract, that entire monthly car payment is permanently attached to your personal profile. When you go to apply for your own funding later, the bank will count your nephew's car against your personal income.
This hidden obligation can completely destroy your borrowing power without you even realizing it. The only way to remove it is to prove to the bank that someone else has paid that specific bill perfectly for at least twelve straight months. To protect yourself from these unexpected surprises, you should regularly monitor your profile through trusted Federal Trade Commission credit resources.
Job Changes and Income Instability
If you switch careers or start a completely new business right before applying, the bank will likely pause your application. They cannot trust your new income until they see a proven track record of stability, even if your new salary is double your old one. They usually want to see at least two years of consistent history in the exact same line of work.
If you are planning to change jobs, you must wait until after your paperwork is completely signed and closed. Timing your life events correctly is a massive part of learning how to avoid common application mistakes. Never give an underwriter a reason to question your ability to earn a steady paycheck.
Actionable Steps to Build a Bulletproof Profile
Start your journey tonight by simply grabbing a blank piece of paper and writing down your real numbers. Be completely honest with yourself about how much you earn and exactly how much you owe to others. You cannot fix a problem if you refuse to look closely at the root cause.
If your percentage is sitting in the danger zone, do not let panic take over your mind. Pick your smallest, most frustrating debt and attack it with every extra dollar you can find this month. By shifting your focus toward small wins, you will build the momentum needed to tackle the larger balances.
You should also take the time to learn about choosing between fixed and variable rates so you make smart choices with your new money. An educated borrower is always the safest investment a bank can possibly make.
If you want to explore more helpful guides and tools, feel free to visit our main homepage at DigitShopy anytime. We are always here to help you navigate these confusing financial waters with clear, honest advice.
Your Next Big Move
You now possess the exact knowledge that wealthy individuals use to leverage the banking system to their advantage. You understand why lenders ask endless questions, and you know exactly how to give them the right answers. It is time to stop guessing and start acting with total confidence.
My biggest turning point happened the moment I stopped viewing banks as my enemy and started viewing them as a simple mathematical puzzle. I organized my income, aggressively cleared out my useless credit card balances, and finally got that stamped approval letter. I know exactly how amazing that relief feels, and I am so excited for you to experience that exact same joy very soon.
Common Questions About Managing Your Approval Ratios
Does my spouse's debt affect my personal calculation?
If you apply for the money entirely by yourself, the bank will only look at your specific income and your specific liabilities. However, if you apply jointly as a couple, both of your incomes and all of your combined debts will be merged into one calculation.
Should I include regular utility bills in this specific math?
No, you should never include your monthly water, electricity, or grocery bills in this particular formula. Banks only care about actual credit obligations like credit cards, auto loans, mortgages, and student loans.
Can I actually get a mortgage with a 45% ratio?
Yes, it is definitely possible to get approved at 45%, especially if you are applying for a government-backed option like an FHA or VA home loan. However, you will likely need a very strong credit score or a massive cash down payment to offset that higher risk level.
How often does my percentage actually change?
Your numbers change every single time you make a payment, take out new credit, or experience a change in your regular salary. The bank will usually pull a fresh snapshot of your exact situation within days of your final closing appointment.
Will paying off a collection account immediately improve my numbers?
Paying off a collection is great for your overall credit health, but it might not immediately change your monthly ratio. This formula only looks at active, recurring monthly minimum payments, not necessarily past-due lump sums.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute financial, legal, or professional advice. Lending requirements and banking policies vary by institution and change frequently. Always consult with a certified financial advisor or a licensed lending professional before making any major financial decisions.