
Facing the Silent Financial Trap
Have you ever felt like you are playing a confusing financial game where someone hid the rulebook? You pay your utility bills early, you make decent money, and yet, your loan applications keep getting tossed in the rejection pile. It is an exhausting cycle that leaves you wondering what you are doing wrong. The truth is, banks judge you on a hidden set of daily habits that happen totally behind your back. Once you know how to control these hidden numbers, you can stop begging for approvals and start getting the offers you actually deserve. Let me show you exactly how this system works.
I felt completely trapped and embarrassed, thinking I was doing everything exactly the right way. The constant worry about money drained my energy and made it genuinely hard to sleep at night. I kept wondering why being a responsible adult never seemed to be enough to get ahead. Every time an unexpected expense popped up, a wave of pure anxiety would crash over me.
So many hard-working people are facing this exact same nightmare every day. You might be working multiple jobs, saving as much as you can, only to get slapped with rejections when you need help the most. It feels like a heavy weight on your chest when a sudden medical bill or car repair drains your bank account. You know you need a temporary loan, but your maxed-out cards stand like a brick wall in your way.
But you are definitely not alone in this struggle, and this problem is highly fixable. Banks and lenders look at very specific numbers to decide if you are a safe bet. Once you understand the hidden rules of the game, you can completely change your financial story.
Quick Action Plan for Your Loan Health:
- Always keep your total credit card balances well below 30 percent of your maximum limit.
- Break your large monthly payments into smaller weekly chunks to beat the bank's reporting dates.
- Treat your credit cards like a debit account by paying off sudden purchases the very next morning.
- Never close your old, unused credit accounts; keep them open to maintain a high available limit.
Breaking Down the Math: Why Your Available Balance Matters
To really fix your borrowing power, we need to look at how lenders judge your daily habits. They do not just care if you pay on time; they care about how much of your available money you are actually using. Think of your total credit limit like a big bucket of water. If your bucket is almost empty because you drank it all, lenders get very nervous about giving you more water.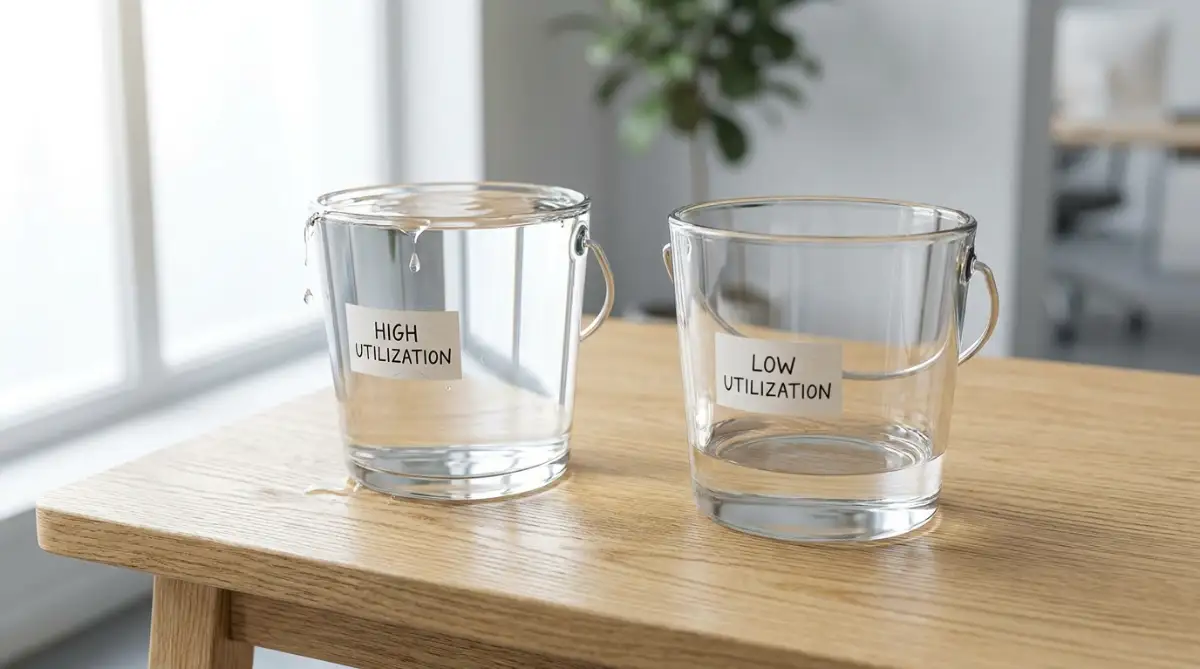
This measurement is officially known as your credit utilization ratio, a key metric actively monitored by the Consumer Financial Protection Bureau (CFPB). It simply compares the amount of money you owe right now to the total amount of money you are allowed to borrow. If you have a credit card with a $1,000 limit, and you spend $800 on it, your ratio is sitting at 80 percent. Financial experts always suggest keeping this number well below 30 percent if you want to look good to banks.
When your ratio climbs too high, lenders assume you are relying too heavily on borrowed money to survive. High utilization makes you look desperate for cash, even if you plan to pay it all back next week. This is exactly why your score drops so fast when you make a large purchase like a television or a new laptop. You might have the cash in your checking account, but the system only sees a maxed-out line of credit.
To make this super easy to understand, here is a quick breakdown of how lenders view your spending habits based on a simple $1,000 credit limit:
The Hidden Danger of Reporting Dates
Many people get confused because they pay their full balance every single month but still see a low score. This happens because credit card companies report your balance to the bureaus on a specific day, usually your statement closing date. If you buy groceries and gas all month, the company reports that high balance before you even get the chance to pay the bill.
So, on paper, you look like a high-risk borrower to anyone checking your file. To beat this system, you have to be slightly more strategic about exactly when you transfer money from your bank to your card.
I used to wait patiently until my official statement arrived in my email before making any payment. My biggest realization was that paying my balance down about three days before the statement closed entirely changed my score. I suddenly appeared to the system as someone who barely used my cards, which made my numbers skyrocket almost overnight.
Practical Strategies for Immediate Loan Health Improvement
Now that we know exactly how lenders view our profiles, it is time to take aggressive action. You do not need to hire an expensive financial advisor or buy a magical software program to fix this. You just need to apply a few scientific, tested methods to your everyday money management.
Expanding Your Total Available Limit
One of the most effective ways to lower your ratio is simply asking for more space. If you owe $3,000 on a card with a $6,000 limit, your ratio is 50 percent. But if you call the bank and get that limit raised to $10,000, your ratio instantly drops to 30 percent without you paying an extra dime.
You can usually request a limit increase right inside your mobile banking application with just a few clicks. Make sure to update your current income if you have gotten a raise at work recently. Banks love to see higher incomes because it proves you have the cash flow to handle more responsibility.
However, you must be honest with yourself before you use this specific strategy. If having a higher limit will tempt you to spend more money, do not do it. The goal is to increase the invisible space, not to buy more clothes or gadgets. Treat that extra limit like a glass display case at a museum; you can look at it, but you cannot touch it.
The Power of Multiple Payments Per Cycle
If your bank denies your request for a limit increase, you can completely bypass the problem by making micro-payments. Instead of making one giant payment at the end of the month, chop it up into smaller pieces. You can set up your bank account to automatically push a payment every single Friday when you get your paycheck.
This keeps your running balance extremely low throughout the entire month. When the credit card company takes their snapshot to report to the bureaus, they will catch your balance at a beautifully low number. This method is amazing because it also stops you from accidentally spending the money sitting in your checking account.
Watch This Expert Breakdown on Managing Balances:
If you are struggling to visualize exactly how statement dates and reporting dates affect your score, taking a few minutes to watch a visual guide can be incredibly helpful. The video below breaks down the exact timeline you need to follow to ensure your payments are actually helping your loan health.
Understanding Different Types of Debt
Not all debt is judged the exact same way when you apply for a new loan or mortgage. Credit cards are known as revolving debt, which means the balance changes every month based on your choices. Lenders pay extremely close attention to revolving debt because it shows your current, daily self-control.
On the other hand, auto loans and student loans are considered installment debt vs revolving credit. You borrowed a fixed amount, and you pay a fixed amount every month until it is entirely gone. While installment debt affects your overall debt-to-income ratio, it does not heavily impact your utilization metrics.
This means you should always prioritize paying down your credit cards before you make extra payments on your car loan. Focusing all your extra cash on your highest revolving balance will give your profile the fastest possible boost. Once the cards are cleared out, you can comfortably switch your focus back to the long-term installment loans.
Strategic Balance Transfers
Sometimes the interest rates on your current cards are so high that making progress feels like running in deep mud. If a huge chunk of your monthly payment goes straight to interest, your principal balance barely moves. In this specific situation, moving the debt to a new environment can be a brilliant move.
Many banks offer promotional balance transfer cards with zero percent interest for over a year. By moving your high-interest debt to one of these clean slates, every penny you pay goes straight toward the actual debt. This aggressively lowers your utilization ratio much faster than staying where you are.
Before doing this, you must carefully read the fine print regarding transfer fees. Most banks charge a small percentage of the total amount you are moving over. You also need a solid, unbreakable plan to pay off the entire balance before the promotional interest period ends.
Common Misunderstandings About Borrowing
The financial world is full of terrible advice passed down from generation to generation. It is completely normal to feel confused when your parents tell you one thing and your bank tells you another. Let us clear up some of the most dangerous myths that might be holding your progress back.
Never leave a small balance on your card just because you think the bank wants to see it. Paying interest is essentially throwing your hard-earned money out the window. Pay the card down to zero before the due date, and enjoy the peace of mind that comes with zero debt.
The Authorized User Strategy
If you are starting from total scratch, or if your numbers have taken a massive hit, doing this alone can take a long time. You can legally piggyback off the excellent financial habits of a trusted family member or spouse. They can add you to their oldest, cleanest credit card as an authorized user.
The moment they do this, the entire positive history of that specific card magically appears on your personal profile. If the card has a massive limit and a very low balance, your overall utilization ratio will instantly improve. You do not even need to carry the physical card in your wallet for this to work perfectly.
Of course, this requires an extreme amount of mutual trust between both people involved. If the primary account holder suddenly maxes out the card or misses a payment, that negative activity will also show up on your report. You should only use this method with someone who is notoriously strict and organized with their personal finances.
Reviewing the Hidden Factors That Hurt You
Sometimes, your numbers refuse to go up even when you are doing everything perfectly. When this happens, there is usually a hidden error quietly destroying your loan health from the shadows. The reporting bureaus handle millions of files every day, and they make shocking mistakes all the time.
Someone else's unpaid medical bill or maxed-out store card might accidentally end up on your personal file because of a simple typo. You have the absolute legal right to dispute any incorrect information you find on your report under federal law. You can easily request a free copy of your data online and comb through every single line.
If you find an account you do not recognize, or a late payment that you actually paid on time, file a dispute immediately. The bureaus are legally required to investigate your claim and remove the data if they cannot prove it is accurate. Cleaning up just one massive error can completely change your borrowing power in a matter of weeks.
Building a Long-Term Financial Shield
Fixing your loan health is not just about getting approved for a shiny new car or a bigger house. It is fundamentally about protecting yourself and your family from unexpected disasters. When your utilization is low and your profile is strong, you always have a reliable safety net waiting for you.
Imagine your home's roof suddenly starts leaking during a massive rainstorm, and the repair costs thousands of dollars. If your cards are maxed out, this situation becomes a terrifying crisis. But if you have been managing your balances wisely, you can easily finance the repair without a second thought.
Maintaining this control requires you to check your statements regularly and adjust your budget when necessary. If you notice your balances creeping up slowly over a few months, you need to catch it early. Cut back on dining out or subscription services until you get those numbers back into the safe zone. Consistency is the only true secret to mastering your financial profile for the rest of your life.
Taking Total Control: Next-Level Borrowing Strategies
Mastering your financial profile is a lot like tending to a garden. You cannot just plant a seed and hope for the best; you have to consistently water it and pull out the weeds. Once you get past the basic rules of paying on time, you can start using advanced tactics to really boost your numbers. These are the exact same methods that top financial experts use to maintain perfect profiles.
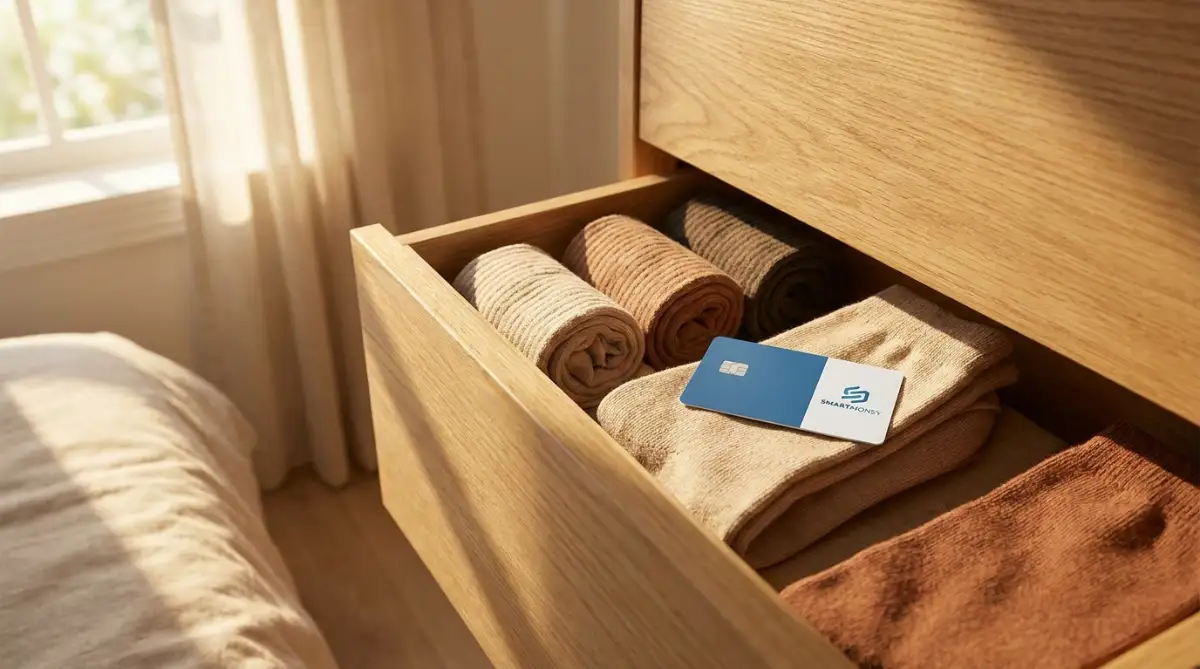
One of my absolute favorite tricks is what I call the "Sock Drawer Strategy" for old accounts. Lenders love to see a long, established history of you borrowing and paying back money successfully. If you have an old card from college with no annual fee, you never want to let the bank close it due to inactivity. Instead, tie a tiny, recurring $5 monthly subscription to that card and set the bill to auto-pay.
After setting up the auto-pay, you can literally put the physical plastic card in your sock drawer and forget about it. This keeps the account active, showing lenders that you have years of positive history. It also keeps your total available limit high, which naturally pushes your utilization ratio down. If you want to dive deeper into official rules about account history, you can always check out federal guidelines on credit history for peace of mind.
Aligning Your Billing Cycles for Maximum Comfort
Most people let the banks dictate when their money is due, which causes a lot of unnecessary stress. If all your major bills are due on the exact same day, it can completely drain your checking account before your next paycheck arrives. You actually have the power to call your card issuers and ask them to change your billing cycle dates.
You should strategically space out your due dates so they align perfectly with your pay schedule. If you get paid on the first and the fifteenth of the month, set half your bills for the third and the other half for the seventeenth. This ensures you always have plenty of cash on hand to make massive payments toward your balances. Creating this smooth cash flow makes helpful steps to transition out of debt feel incredibly natural and effortless.
The Hybrid Spending Method
Another brilliant strategy is treating your revolving accounts exactly like a debit card. Many people get into trouble because they mentally separate their borrowed money from their actual bank balance. They swipe their card all month long and then feel shocked when the massive bill finally arrives in their inbox.
To completely prevent this shock, start making payments immediately after you make a purchase. If you buy a week's worth of groceries for $150 on a Tuesday, log into your banking app on Wednesday and pay that $150 right back. This hybrid method gives you the fraud protection of a real card while keeping your running balance at absolute zero.
For example, my friend Sarah used this exact trick last year when she was trying to buy a car. She wanted the cash-back rewards from her daily shopping, but she refused to let the bank see a high balance. So, she paid off her grocery charges straight from her banking app the very next morning. The bank saw constant activity, but they reported a brilliant $0 balance at the end of the month, which pushed her score up enough to secure a rock-bottom interest rate on her auto loan.
Mastering the Art of Account Mixing
Lenders do not just look at how much you borrow; they also look at the different types of accounts you manage. Having five different store cards might seem like a lot of borrowing power, but lenders prefer to see variety. They want proof that you can handle short-term revolving debt as well as long-term installment loans.
If you already have a mortgage or a car loan, you are perfectly fine in this department. But if you only have one type of account, you might want to understand the difference between installment and revolving accounts to plan your next move. Adding a small, manageable personal loan to consolidate debt can actually improve your mix and make your profile look much stronger. Just make sure you are always relying on national consumer finance resources to verify the safety of any new borrowing strategy.
The Hidden Traps That Destroy Borrowing Power
Fixing your financial health requires a lot of hard work, but destroying it only takes one bad decision. I have seen so many hard-working people accidentally ruin their borrowing power because they listened to terrible advice from a friend. When you are trying to buy a house or get an affordable car, a single mistake can cost you thousands of dollars in extra interest.
The most heartbreaking part is that people usually make these mistakes with the best intentions. They think they are doing the responsible thing, but the strict banking algorithms see it completely differently. We need to expose these dangerous pitfalls right now so you never fall into them.
The "Revenge Closure" Mistake
Imagine you finally pay off a card that has been haunting you for three long years. You feel so proud, and in a moment of pure triumph, you call the bank and cancel the account completely. You think you are protecting yourself from future debt, but you just shot your own profile right in the foot.
When you close that account, all of that available limit instantly disappears from your permanent file. If you have balances on any other cards, your overall utilization ratio will suddenly spike through the roof. Never close an old account just because you are mad at it. Unless the card charges a massive annual fee that you cannot afford, leave it open and completely empty.
The Danger of the "Just This Once" Purchase
We all have moments where we want to treat ourselves or our family to something special. A spontaneous holiday trip or a brand-new television might seem harmless if you promise to pay it off next month. But if that purchase pushes your balance past the 30 percent safety zone, your file takes an immediate hit.
If you happen to be applying for a new apartment or a vehicle during that exact same month, you will likely get denied. Lenders do not care about your promises to pay it off later; they only care about what the math shows today. If you need sudden cash for a real crisis, always read up on applying for emergency funding safely before you just swipe your plastic.
Buying Furniture Before the Ink Dries
This is probably the most common and devastating mistake in the entire real estate world. You finally get approved for a beautiful new home, and you are waiting a few weeks to officially close the deal. You get excited and run out to finance a brand-new living room set for your new house.
Right before you sign the final house papers, the mortgage company does one last check on your profile. They see the massive new furniture debt, realize your utilization ratio just exploded, and they completely cancel your home approval. Until the absolute final paperwork is signed and keys are in your hand, you must freeze all of your spending.
The Blind Co-Signing Disaster
We naturally want to help the people we love when they are struggling to get on their feet. When a family member asks you to co-sign for a new car because their numbers are too low, saying yes feels good. But from a legal perspective, you are taking on 100 percent of the risk with absolutely none of the reward.
If your relative misses a single payment, or if they max out the limit, that terrible activity goes straight onto your permanent record. You could lose your own ability to borrow money simply because someone else was irresponsible. If you want to help a friend, teach them how to negotiate better terms with your lender rather than risking your own financial safety net.
Ignoring the Silent Background Errors
Many people operate under the dangerous assumption that banks and reporting agencies never make mistakes. They just assume their numbers are completely accurate and never bother to actually look at the raw data. This lazy approach can quietly cost you a massive amount of money over your lifetime.
Identity theft is incredibly common, and sometimes a random debt collection agency will stick a bogus fee on your file. If you are not actively monitoring y