The Hidden Stress of Medical Insurance Claims
Listen, opening a hospital bill shouldn't feel worse than the actual surgery. But when my husband got out of the hospital last year, the massive stack of confusing insurance papers almost broke me. I spent nights stressing over random denial letters before I finally figured out the exact loopholes they use to reject us. Today, I am going to show you exactly how I fought back and got my claims paid, without needing a law degree.
My Quick Blueprint for Winning Your Claims
- Double-check everything: Treat your claim forms like a strict math test. One wrong birth year can delay your money for months.
- Never accept the first "No": Over half of all denied claims just need a simple missing detail to get approved.
- Get a doctor's backup: Ask your clinic for a "Letter of Medical Necessity" to easily override automated rejections.
- Keep a digital trail: Always write down the Reference Number and the exact name of the agent you speak with on the phone.
Why Most Claims Get Lost in the Shuffle
Many people struggle because they approach the process without a clear strategy. They assume that simply submitting a bill is enough to get a response. Unfortunately, small mistakes often lead to massive delays. Here is why so many patients feel stuck:
- Incomplete Documentation: Missing a single signature or a date can trigger an automatic rejection.
- Lack of Policy Knowledge: Not knowing what your specific plan covers often leads to filing claims that are destined to be denied.
- Misunderstanding Codes: Medical bills are filled with technical jargon that most people do not understand.
- Delay in Submission: Waiting too long to file can move your case past the required deadline.
Insurance Myths vs. Facts You Need to Know
The Mental Toll of Insurance Uncertainty
The stress of waiting for a claim approval is more than just financial. It affects your daily life and your ability to focus on your health.
- Constant Anxiety: You spend your days checking emails and making phone calls instead of resting.
- Loss of Trust: Repeated denials make you feel like the system is working against you.
- Confidence Issues: You might stop seeking necessary care because you fear the financial outcome of another rejected claim.
- Impact on Family: The financial strain creates tension at home, making a difficult recovery even harder.
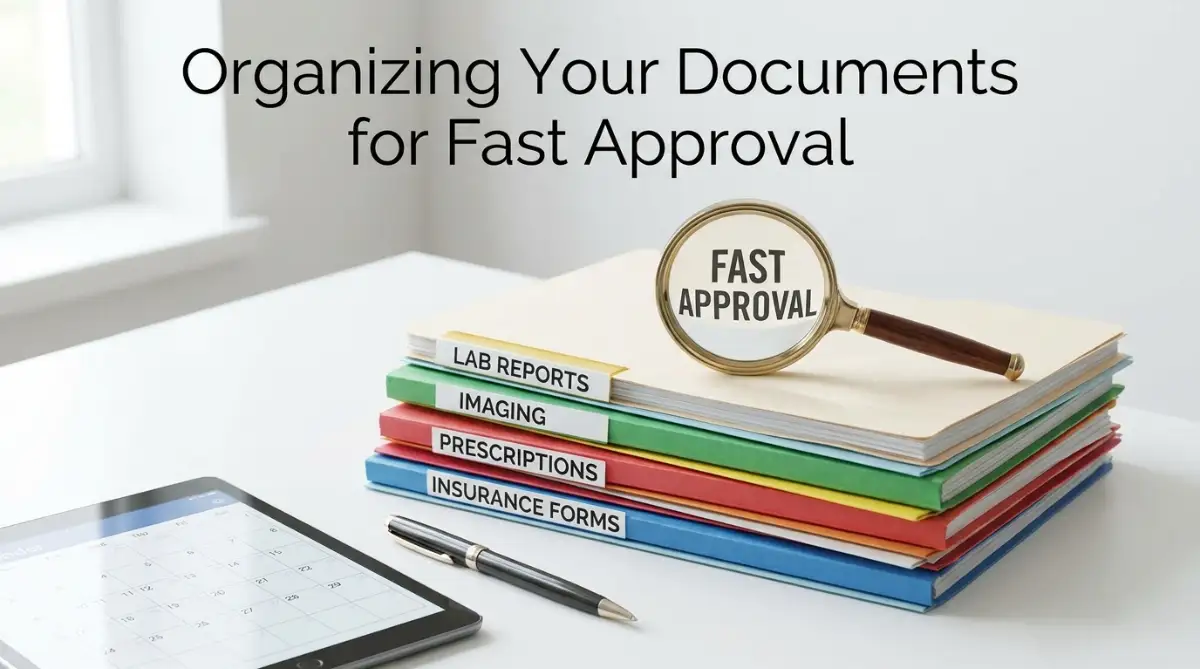
Step 1: Building a Strong Foundation for Your Claim
The first step in any successful claim is preparation. You must treat your medical file like a legal document. Before you even submit a form, take the time to organize every single piece of information.
Create a Dedicated Filing System
Do not rely on loose papers or digital emails scattered in your inbox. Create a physical folder or a dedicated digital folder on your computer for each specific incident. Label everything by the date of service and the name of the provider.

When you have everything in one place, you remove the chaos. If an insurance agent asks for a specific test report, you can provide it instantly. This shows them that you are organized and serious about your request.
Understand Your Policy Details
Before you file, take twenty minutes to read your Summary of Benefits. Most people skip this because it looks boring, but it contains the secret to your success. Look specifically for "Exclusions" and "Coverage Limits."
Knowing what is excluded prevents you from filing claims that will definitely be denied. You can also highlight the exact services that are fully covered. When you quote your policy back to the agent, you speak their language. This makes your claim much harder to ignore.
Step 2: Mastering the Art of Documentation
Documentation is the bridge between a rejected claim and a paid one. If your paperwork is incomplete, the insurance company has a valid reason to pause your file .
Verify Every Detail Before Submission
Errors as small as a misspelled name or a wrong date can stop the entire process. Before you click "submit" or mail your forms, double-check every field. Cross-reference the dates on your doctor’s bill with your pharmacy receipts.
If the dates do not align, the system flags your claim for "review." This review process can take weeks. By ensuring your math and dates are perfect, you bypass the manual review queue entirely.
I used to think the insurance company would just figure out small mistakes on their own, but a single typo on my birth year once delayed my payout for three long months! My biggest realization was that treating my claim forms like a strict final exam—double-checking every single comma and date—is the absolute best shortcut to getting paid faster.
Obtain Detailed Medical Notes
Sometimes a bill is not enough to get approval. Always ask your doctor’s office for itemized statements and clinical notes. These documents explain why a specific procedure was necessary.
Insurance companies want to see "Medical Necessity." If your doctor writes a brief note explaining that a test was required for your specific condition, the claim has a much higher chance of success. Do not be shy about asking the front desk for these summaries. It is your right as a patient to have clear records.
Quick Question: What exactly should I say to the billing department?
My Answer: Keep it super simple. Pick up the phone and say, "Hi, my claim for [Date of Service] got denied. Can you tell me the exact missing CPT code so we can resubmit this today?" You will be amazed at how fast they help you when you ask for specific codes instead of just complaining about the bill.
Step 3: Proactive Communication Strategies
Filing a claim is not a "set it and forget it" task. You must become your own advocate.
The Power of Follow-Up
Most people submit their forms and wait for a letter in the mail. Do not do this. Set a reminder on your phone to check the status of your claim after five business days.
When you call the insurance provider, always ask for the Reference Number of your call. Write it down and keep it in your folder. If you speak to a representative, ask for their name or ID number. Having this information creates accountability.
What to Do If You Get a Denial
A denial is not the end of the road. It is often just a request for more information. Read the "Explanation of Benefits" (EOB) carefully to understand why they said no .
Often, it is simply a missing piece of data. Call the company, explain that you have the missing information, and ask how to submit it for a re-evaluation. Most claims that are initially rejected are actually approved once the missing detail is added. Stay calm, stay polite, and keep moving forward.
Step 4: Mastering the Appeal Process Like a Pro
If the thought of fighting an insurance denial makes you want to pull your hair out, watch this quick video below to see exactly how simple a successful appeal can be. Once you finish watching, keep reading to discover the best digital tools to track your money without losing your mind!
Most people stop the moment they see the word "Denied" on a piece of paper. This is exactly where you can turn the tide in your favor by understanding how to file a formal appeal.
Think of an appeal not as a complaint, but as a correction of missing facts. Insurance companies often use automated systems that flag claims for minor inconsistencies. You simply need to provide the missing context to override that machine decision.
Sneaky Insider Tip: Did you know you can ask your insurance company for a "Peer-to-Peer review"? If they deny your claim, you can request that your actual doctor speaks directly on the phone with a doctor who works for the insurance company. When two doctors talk, the insurance side usually drops the silly technical excuses and approves the treatment!

Getting Expert Help for Your Appeal
If your claim is complex, reach out to your doctor’s billing department directly. Most clinics have dedicated staff whose only job is to handle insurance disputes. They often know the exact proper medical billing codes that will trigger an approval.
Ask them to write a "Letter of Medical Necessity" on your behalf. This one document can be the difference between a paid claim and a massive out-of-pocket expense. A doctor’s professional signature adds weight that an individual patient's voice simply cannot match.
Maintaining Your Coverage Health
To stay ahead, you must treat your health insurance coverage as an active part of your wellness plan. Do not wait for a crisis to check your policy documents.
Set a recurring calendar alert to review your deductibles and maximum limits at least twice a year. This keeps you informed about how much you need to contribute before your insurance kicks in. Being proactive prevents the "sticker shock" that hits many families when a large bill arrives unexpectedly.
Step 5: Utilizing Technology for Better Management
We live in a time where digital tools can do the heavy lifting for us. Stop relying on your memory or a pile of paper in a kitchen drawer.
Using Dedicated Apps to Track Claims
Many insurance providers now offer mobile apps that allow you to track your claims in real-time. If yours does not, use a simple cloud-based notes app to keep a log of every interaction.
Record the date, the name of the representative, and the outcome of the call. This digital trail is your safety net. If an agent tells you a claim is "in progress," you can cite the exact date and person who told you that previously.
Keeping Your Financial Life Balanced
A medical emergency can put a temporary strain on your finances, which is why managing your personal budget is essential. When you know exactly how much you can afford, you can negotiate payment plans with hospitals much more effectively.
Hospitals would rather have a steady, monthly payment than deal with a collections agency. Never be afraid to ask for a discount if you are paying out-of-pocket. Many billing departments have internal programs to help patients lower their total burden.
Pitfalls That Trip Up Even Smart Patients
Even with the best intentions, many people make simple mistakes that stall their claims. Avoiding these common traps will save you hours of frustration.
- Waiting for the "Right Time" to File: You should submit your claims as soon as you receive the service. Delaying increases the risk of losing receipts or missing the provider’s filing deadline.
- Assuming the Doctor Handled It: Many patients think the hospital submits every bill automatically. Always ask the front desk, "Will this be billed to my insurance, or do I need to file it myself?"
- Failing to Verify Coverage for Specific Doctors: Just because a hospital is in your network, it does not mean every doctor inside that building is. Always check the status of your specialist before the appointment starts.
- Ignoring the Explanation of Benefits (EOB): Do not throw these away thinking they are just bills. They explain why a claim was paid or denied and are your main tool for tracking your progress.
- Giving Up After One Denial: Most people stop at the first hurdle. Always ask for a phone number or a specific email address to submit additional information for a second review.
Ignoring these pitfalls can lead to a snowball effect of debt and stress. When you catch these errors early, you protect your bank account and your peace of mind .
Your Path to Financial Peace of Mind
Managing your medical claims successfully is a skill that anyone can learn. By staying organized and keeping a clear log of your interactions, you become a master of the process.
You now have the tools to talk to your insurance company with confidence. Remember that your health is your top priority, and the paperwork is just a temporary hurdle to clear. Start by creating your dedicated folder today and checking your policy details.
Small, consistent steps lead to big results. You have the power to stop the stress and handle your medical finances like a pro. Start your journey toward financial clarity right now.
Taking control of my medical bills changed my life from a state of constant panic to total peace of mind, and I know you can do it too. Grab a simple folder today, print out your policy, and take that easy first step. You have already survived the health scare, so do not let the paperwork win!
Disclaimer: The information provided in this article is for educational purposes only and does not constitute professional financial or legal advice. Insurance policies vary significantly by provider and region. Always review your specific policy documents or consult with a licensed insurance agent regarding your individual circumstances.
THANK YOU FOR READING PATIENTLY