
The Hidden Weight of a Low Financial Reputation
Your credit score is silently stealing your money. A low three-digit number shouldn't define your worth, but right now, it dictates your interest rates, your apartment approvals, and sometimes even your job prospects. You might think you need a high-paying job to get an 800+ score, but that is simply not true. You just need to understand the hidden math banks use to grade you. Today, we are skipping the basic fluff and looking at the exact loopholes, payment hacks, and dispute tactics that force the credit bureaus to increase your score fast. Let's get straight into it.
The truth is, having bad credit is incredibly expensive. You are forced to pay the highest interest rates on everything.
Let us look at a simple real-life example. If you buy a $20,000 car with an excellent rating, your interest rate might be 4%. Over five years, you pay about $2,100 in interest.
If you have a poor rating, that same car loan might carry a 15% interest rate. You will end up paying nearly $8,500 in interest. That is over $6,000 stolen from your pocket simply because of a three-digit number.
The system is designed to keep you trapped. When you have bad credit, everything costs more, making it harder to save money. Because you cannot save money, you rely on high-interest payday loans, which ruins your score even further.
Fast Track: What You Will Learn Today
- The Mail Rule: Why you should always dispute report errors using physical, certified mail instead of online buttons.
- The 10% Sweet Spot: How keeping your credit utilization under 10% forces the fastest score jump.
- The Closing Date Hack: The exact day you need to pay your credit card bill (Hint: It is NOT your due date).
- Piggybacking: How to legally borrow a family member's perfect payment history to boost your own thin profile.
How to Hack the Credit System Safely and Legally
Before we get into the details, you should watch this. It’s a great visual breakdown of the exact steps I’m about to show you, and it makes the whole process feel so much easier to handle. Watch it and then keep reading to see how to apply these secrets yourself!
Now that we understand the deep impact of a low score, it is time to take your power back. You do not need a finance degree to fix this.
You just need a clear, actionable plan. We are going to look at the most powerful, scientifically proven methods to force your score upward.
Myth vs. Fact: What Actually Helps Your Score?
Before you do anything, let's clear up some massive misunderstandings that end up hurting people's reports.
Expert Insight: The Credit Bureau Myth
Many people think the credit bureaus (Equifax, Experian, TransUnion) are government agencies looking out for your best interests. They are not. They are private, for-profit companies. Their customers are banks, not you. They make mistakes all the time, and it is entirely your responsibility to catch them.
Step 1: Hunt Down and Destroy Reporting Errors
Think of your credit report as a financial report card. Now, imagine if your teacher accidentally gave you another student's failing grades. Would you just accept it? Of course not.
Surprisingly, a Federal Trade Commission study found that one in five consumers has an error on at least one of their reports. That means 20% of people are suffering from bad credit that isn't even their fault.
Errors happen constantly. Someone with a similar name might have their defaulted loan placed on your file. A hospital might send a bill to collections even after your insurance paid it.
Your first mission is to pull your official reports. You can get these for free once a week from AnnualCreditReport.com.
Do not rely entirely on free app trackers. While apps are great for monitoring, they only provide a summary. You need the deep, detailed data from the official bureaus.
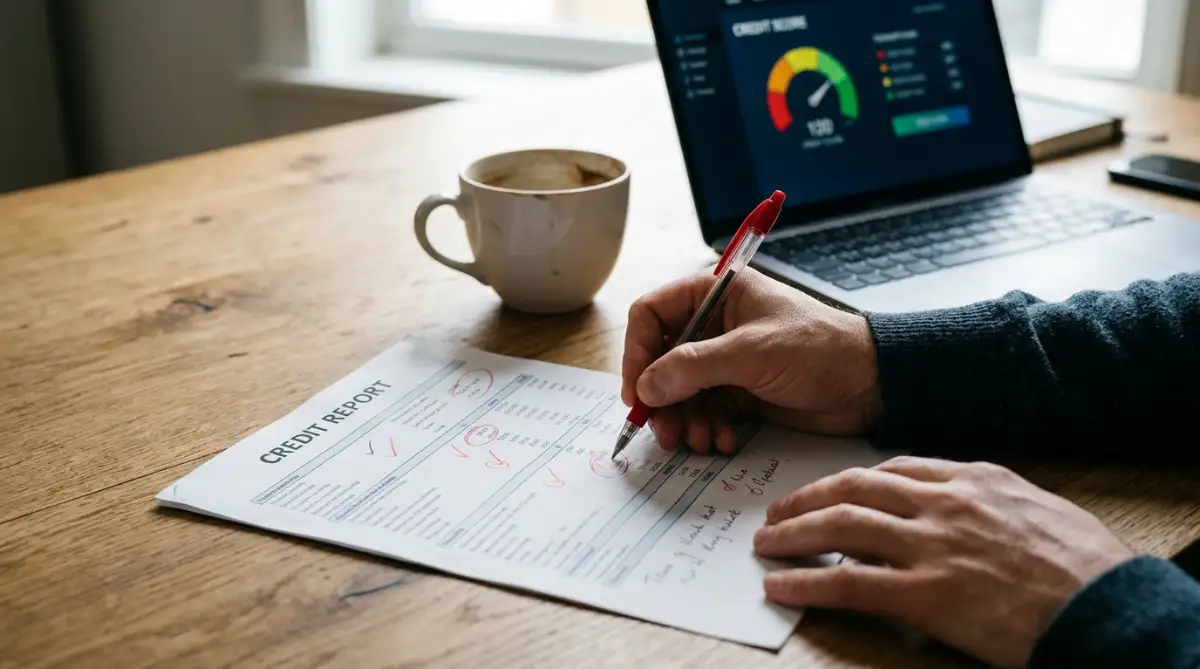
Once you have your reports in front of you, grab a red pen or a digital highlighter. You are going to look for these specific red flags:
- Personal information errors: Wrong addresses, misspelled names, or employers you never worked for. This is often the first sign of mixed files or identity theft.
- Account status errors: Accounts listed as "late" when you have bank statements proving you paid on time.
- Duplicate accounts: The exact same collection account listed two or three times by different agencies, dragging your score down multiple times.
- Zombie debt: Accounts that are too old to be legally reported (usually past seven years) but are mysteriously still showing up.
When you find an error, you must dispute it. But do not use the online dispute buttons provided by the bureaus.
Why? Because checking those boxes strips away some of your legal rights. Instead, write a physical letter. Yes, a real, old-school letter sent through certified mail.
In your letter, state exactly what is wrong, provide your proof (like a bank statement), and demand the item be removed or corrected. Under the Fair Credit Reporting Act, the bureaus have 30 days to investigate. If the creditor cannot prove the debt is accurate, the bureau must delete it by law.
This single step can sometimes boost your rating by 30 to 50 points in a single month.
Step 2: Master the Art of Credit Utilization
One thing I learned the hard way is that paying off a debt isn't always enough to fix the damage. I once paid a collection agency in full, thinking my score would jump, but it didn't budge because I forgot to ask for a "pay-for-delete" agreement. My pro tip: Never send a single cent to a collector until you have a written promise that they will completely wipe the negative mark off your report.
If you want to see the fastest possible jump in your score, you must master something called the Credit Utilization Ratio. This factor alone makes up 30% of your total score.
So, what is it? It is simply the math of how much credit you are using compared to how much you have available.
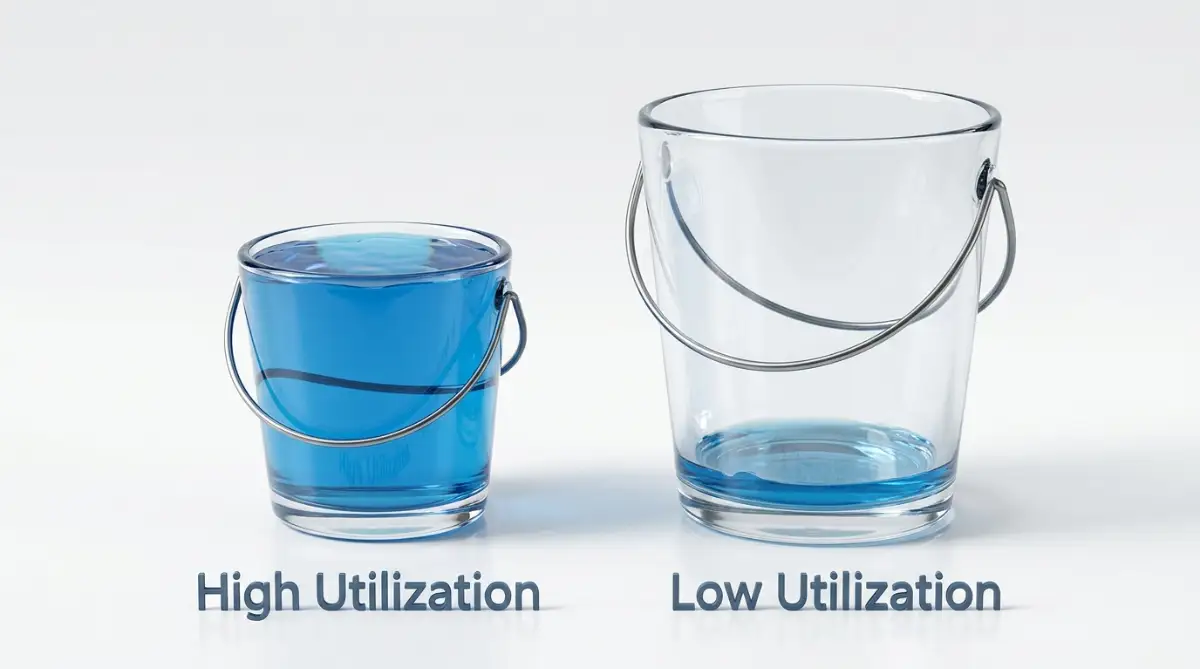
Let us use a simple bucket analogy. Imagine you have a bucket that can hold 10 gallons of water. This represents your total credit limit of $10,000.
If you put 9 gallons of water in that bucket, it is almost full and very heavy. The banks see this and panic. They think, "This person is struggling and relying too much on borrowed money!" Your score drops significantly.
Now, imagine that same bucket only has 1 gallon of water in it. The banks relax. They see you have access to a lot of money, but you are disciplined enough not to use it. Your score goes up.
Most traditional advice tells you to keep your balances below 30% of your limit. That advice is average, and we want exceptional results.
If you want a top-tier score, you need to keep your utilization under 10%. If your limit is $1,000, never let the reported balance cross $100.
Here is a brilliant strategy if you cannot afford to pay off large balances right away: Ask for a limit increase.
Call your card issuer and politely ask them to increase your credit limit. If you have been paying on time, they often say yes.
Let us say your current card has a $1,000 limit and a $500 balance. Your utilization is 50%, which is hurting you. If the bank increases your limit to $2,000, that exact same $500 balance is now only 25% utilization.
You changed your ratio instantly without paying an extra dime. Your score will naturally reflect this improvement within weeks.
Step 3: Hack the Statement Closing Date
This is a secret strategy that completely changes the game. Most people think as long as they pay their bill by the "Due Date," their credit score is safe.
This is a massive misunderstanding of how the system works.
Your credit card company reports your balance to the bureaus once a month. But they do not report it on your due date. They report it on your Statement Closing Date.
Here is how a normal, uninformed person operates: Meet Sarah. Sarah buys a $800 laptop on her credit card, which has a $1,000 limit.
Her statement closes on the 5th of the month. Her due date is not until the 25th of the month.
Sarah is a responsible person. She pays the entire $800 on the 20th, well before her due date. She pays zero interest. But when she checks her credit score, it has dropped!
Why? Because on the 5th, the bank took a snapshot of her account. They saw an $800 balance on a $1,000 limit (80% utilization). They sent that terrible data to the credit bureaus.
Even though she paid it off later, the damage was already done for that month.
Here is the correct way to handle this. You need to find out your exact Statement Closing Date. You can find this on your PDF statement or by calling customer service.
Once you know that date, pay your balance three days before the statement closes.
If Sarah had paid her $800 on the 2nd of the month, the bank would take their snapshot on the 5th and see a $0 balance. They would report 0% utilization to the bureaus.
By simply shifting her payment date a few weeks earlier, she protects her financial reputation completely.
If you want to be extra safe, you can make two payments a month. Pay half of your balance exactly 15 days before the closing date, and pay the remaining balance three days before the closing date. This keeps your reported balance incredibly low and shows a fantastic payment history.
This tiny shift in your daily habits costs absolutely no extra money. It just requires a small adjustment in your calendar.
Your 30-Day Credit Card Payment Cheat Sheet
Not sure when to pay? Use this simple timeline so you never accidentally report high usage to the bureaus again:
Step 4: Become an Authorized User on a Golden Account
If you are just starting out, or if you have a very damaged history, building trust from scratch takes time. But there is a legal shortcut known as "piggybacking."
You can ask a trusted family member or spouse to add you as an Authorized User on one of their oldest, most pristine credit cards.
When they add you to their account, the entire history of that specific card is magically copied and pasted onto your credit report. Imagine your mother has a credit card she opened 15 years ago. She has never missed a payment and keeps the balance at zero.
The moment you are added as an authorized user, your credit report suddenly shows 15 years of perfect payment history. The bureaus calculate this new data, and your score shoots up.
However, you must be extremely careful with this strategy. It is a double-edged sword.
If the primary account holder misses a payment or maxes out the card, that negative data will also show up on your report and drag you down. You must only ask someone who has impeccable financial habits.
Furthermore, you do not even need them to give you the physical card. They can cut the card up the moment it arrives in the mail. You do not want to spend their money; you only want to borrow their good reputation.
This is hands-down the fastest way to add positive age and payment history to a thin or damaged file. It is entirely legal, and banks fully expect families to use this method to help each other.
By combining these four strategies—disputing errors, manipulating your utilization ratio, timing your payments perfectly, and leveraging authorized user accounts—you build an unstoppable foundation.
You stop playing defense and start playing offense. You force the bureaus to update your data with positive, high-scoring markers.
But this is only the beginning of your journey. To truly bulletproof your financial life and reach the elite 800-club, you have to understand how to handle debt properly.
Next-Level Strategies for Maximum Score Growth
Once you master the basics of utilization and dispute management, you are ready for the big leagues. These advanced strategies separate average financial profiles from top-tier ones.
Most people stop trying once they hit a "good" rating. But we want you to reach the excellent category, where banks practically beg you to take their money. Let us explore some powerful secrets that industry insiders use to build massive financial trust.
The Power of a Perfect Credit Mix
Banks love predictability. They want to know you can handle different types of financial responsibilities at the same time.
This is where your credit mix comes into play. It makes up about 10% of your total score calculation according to major scoring models. While 10% sounds small, it is exactly what pushes a good score up to a truly exceptional one.
Think of your profile like a balanced diet. If you only eat apples every day, you are missing out on other necessary nutrients.
If you only have revolving accounts (like credit cards), lenders see a limited picture. They want to see how you handle installment accounts too.
An installment account is a loan with a fixed monthly payment. Auto loans, mortgages, and student loans fall into this category. When you successfully manage both revolving and installment accounts, you prove you are financially mature.
But what if you do not need a car or a house right now? You should never go into massive debt just to build your profile.
Instead, look into a credit builder loan. These are small, safe loans designed entirely to help you build history. You borrow a small amount, the bank holds it in a frozen savings account, and you make tiny monthly payments.
Once the loan is paid off, you get your money back, and you have 12 months of flawless installment history on your record. This is a brilliant way to prepare your profile before getting approved for a personal loan in the future.
The Goodwill Letter Strategy
Sometimes, life happens. You might get sick, lose a job, or simply forget a due date during a highly stressful week.
Suddenly, a 30-day late payment shows up on your report. A single late payment can drop an excellent score by up to 100 points instantly. Most people panic and assume they have to wait seven years for this negative mark to fall off. That is completely false.
If you have an otherwise perfect history with a specific bank, you can use a "Goodwill Adjustment Letter." This is a polite, professional letter sent directly to the bank's executive offices.
You are not disputing the late payment, because you admit it actually happened. Instead, you are asking for forgiveness.
In your letter, explain the unique hardship you faced during that specific month. Highlight your long history of loyalty and on-time payments with their company. Then, respectfully ask them to remove the late mark as a courtesy.
Banks are run by human beings. When they see a genuine apology from a loyal customer, they often grant these goodwill adjustments. To increase your chances, mail your letter to multiple executives within the company. Finding their corporate mailing addresses is usually just a quick internet search away.
Protecting Your Profile with Strategic Freezes
Every time you apply for new financing, a bank performs a "hard pull" on your report. Each hard inquiry can drop your score by a few points.
While one or two inquiries are harmless, having six or seven in a short period looks terrible. Lenders see this as desperate behavior.
You can stop unauthorized inquiries entirely by placing a security freeze on your files. The Consumer Financial Protection Bureau (CFPB) strongly recommends this step for ultimate financial protection.
A freeze locks your file so no one can access it. Even if an identity thief gets your social security number, they cannot open an account in your name.
When you actually want to apply for something, you simply log into the bureau's app and "thaw" your file for 24 hours. This puts you in absolute control of who sees your data and when they see it.
The Dangerous Traps That Destroy Your Progress
Even with the best intentions, you can accidentally ruin months of hard work in a single afternoon. The financial system is full of hidden traps designed to catch uninformed consumers.
To protect your rising score, you must actively avoid these common pitfalls. Let us walk through the most dangerous mistakes people make.
Closing Old and Unused Accounts
This is the most common and devastating mistake consumers make. You finally pay off a credit card you have had for ten years, and you decide to close it so you never use it again.
Do not do this.
Your score heavily relies on the average age of your accounts. The older your file, the more trustworthy you appear to lenders.
When you close your oldest card, you immediately wipe out a huge chunk of your positive history. Your average account age drops, and your score plummets.
Additionally, closing an account instantly lowers your total available limit. This automatically drives up your overall utilization ratio on your remaining cards.
If you hate a specific card, simply cut the physical plastic into pieces and throw it away. Delete the card number from your phone and online shopping accounts. Let the account stay open and completely empty so it continues to age beautifully on your report.
Ignoring Small Nuisance Collections
Many people think a tiny $40 medical bill or a forgotten $20 utility bill will not matter. They assume lenders only care about huge debts. This is a